The new rules of bank loyalty: 10 findings shaping customer choice
by Marta Trias Gray | 01 Oct 2026
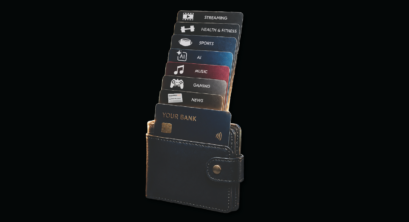
New Bango research reveals how subscription benefits can influence customer choice and strengthen bank loyalty.
Bank customers may stay for decades, but long tenure does not always mean active loyalty. Switching is easier, digital banks have expanded consumer choice and many customers now spread their financial lives across several accounts. In that environment, banks need to give people a stronger reason to make one account their primary relationship.
New Bango research, “Banking on loyalty”, among 4,000 consumers in the US and UK, shows how subscriptions are beginning to influence that decision. Customers already spend on subscriptions every month, giving banks a clear opportunity to offer benefits they understand and use regularly.
“Banking on loyalty” explores how subscription bundling can support acquisition, engagement and revenue, as well as the role banks could play as subscription management becomes increasingly shaped by AI.
Here are ten findings from the research.
1. Free subscriptions could give customers a reason to switch
Consumers often keep the same checking account for years, which makes their willingness to switch for subscription benefits particularly significant. Bango research found that 31% would switch financial provider for free access to their favorite subscriptions, while 32% would do so for free streaming services and 28% for discounted streaming.
This gives banks a tangible way to attract new customers because, unlike points or rewards whose eventual value may take time to understand, a subscription benefit is connected to a service people already use and pay for.
When that value is clear at sign-up and continues throughout the relationship, it can support acquisition while giving customers an ongoing reason to engage with the bank.
2. Subscription benefits appeal across generations
3. Subscription savings can strengthen loyalty
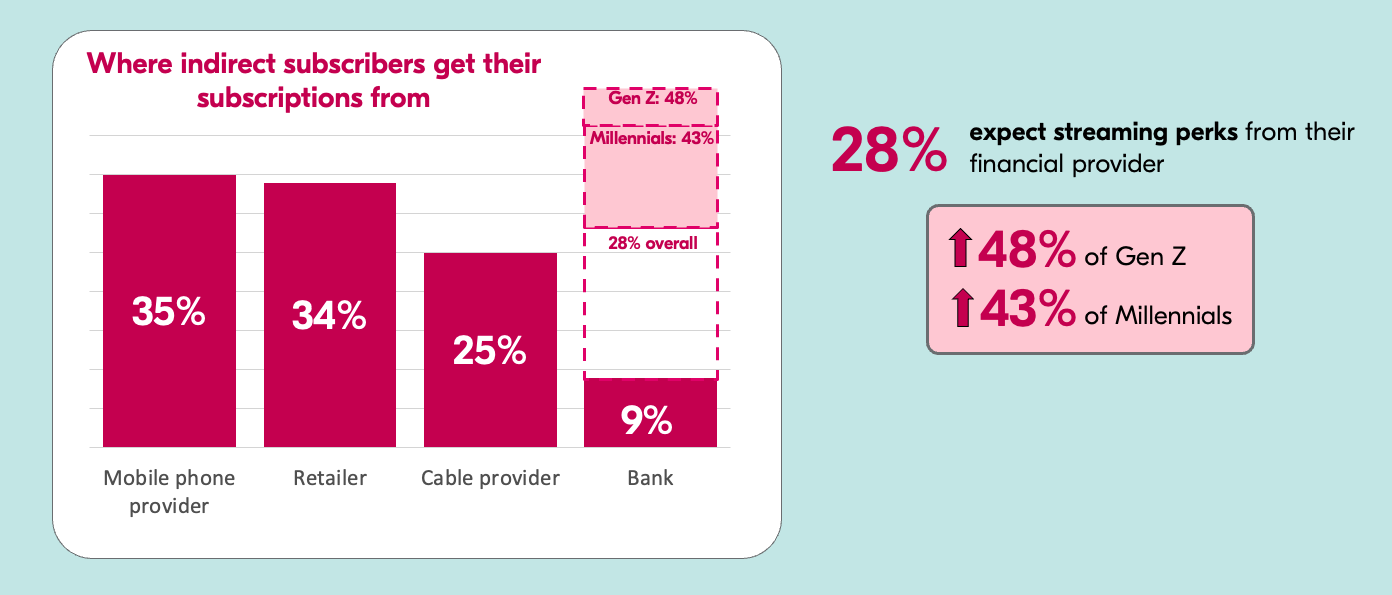
4. The expectation gap is now impossible to ignore
This shows how far banks currently lag behind other subscription distributors, but it does not reflect what customers want from them. More than a quarter, 28%, expect their financial provider to include streaming as a benefit, rising to 43% among Millennials and 48% among Gen Z.
Customers already understand subscription bundling because they receive subscriptions through mobile providers, retailers and pay-TV companies. Banks now have an opportunity to meet the same expectation by giving customers greater access to subscription benefits through their financial provider.
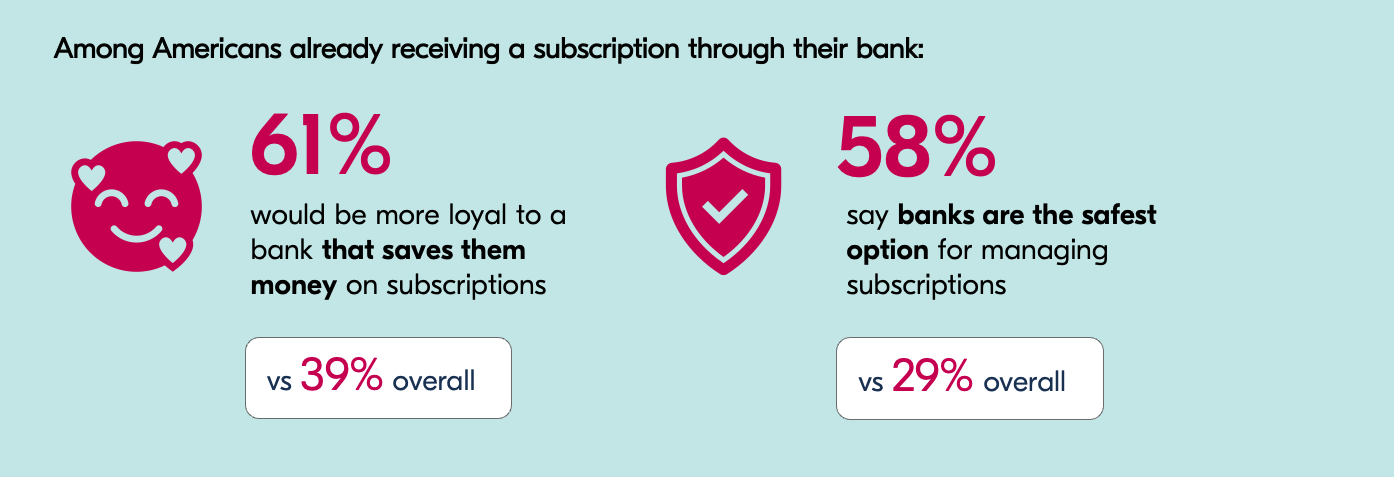
5. Customers already bundling through banks expect more
These customers also have greater confidence in banks as subscription managers, with 58% describing them as the safest option for managing subscriptions in one place. This suggests that customers who already receive subscription benefits from their bank are more open to the bank playing a broader role in how those services are managed.
Banks that already offer a subscription benefit can build on that relationship by moving beyond a one-off redemption. Providing more choice, simpler management and clear upgrade options gives customers more reasons to return to the banking environment and explore additional services.
6. One place to manage subscriptions is part of the value
Saving money is an important part of the appeal, but customers also want an easier way to manage multiple subscriptions. More than a third, 36%, would like one sign-in and one monthly bill covering all their services, showing that convenience matters alongside price.
Banks are well placed to provide this experience because they already manage the payments behind many of these subscriptions. Bringing discovery, activation and ongoing management into the banking app could help customers understand what they pay for, make changes more easily and manage their services alongside the rest of their finances.
This would also give the bank a more valuable role in the customer relationship, as the benefit would come from an experience customers use regularly rather than a discount they redeem once.
7. A voucher is not the same as managing a subscription
This may generate a redemption, but it gives the bank little ownership of what happens next. The bank funds the incentive while the subscription provider gains the activation, ongoing engagement and any future upgrade. Customers are also left navigating different registration processes, account details and cancellation journeys.
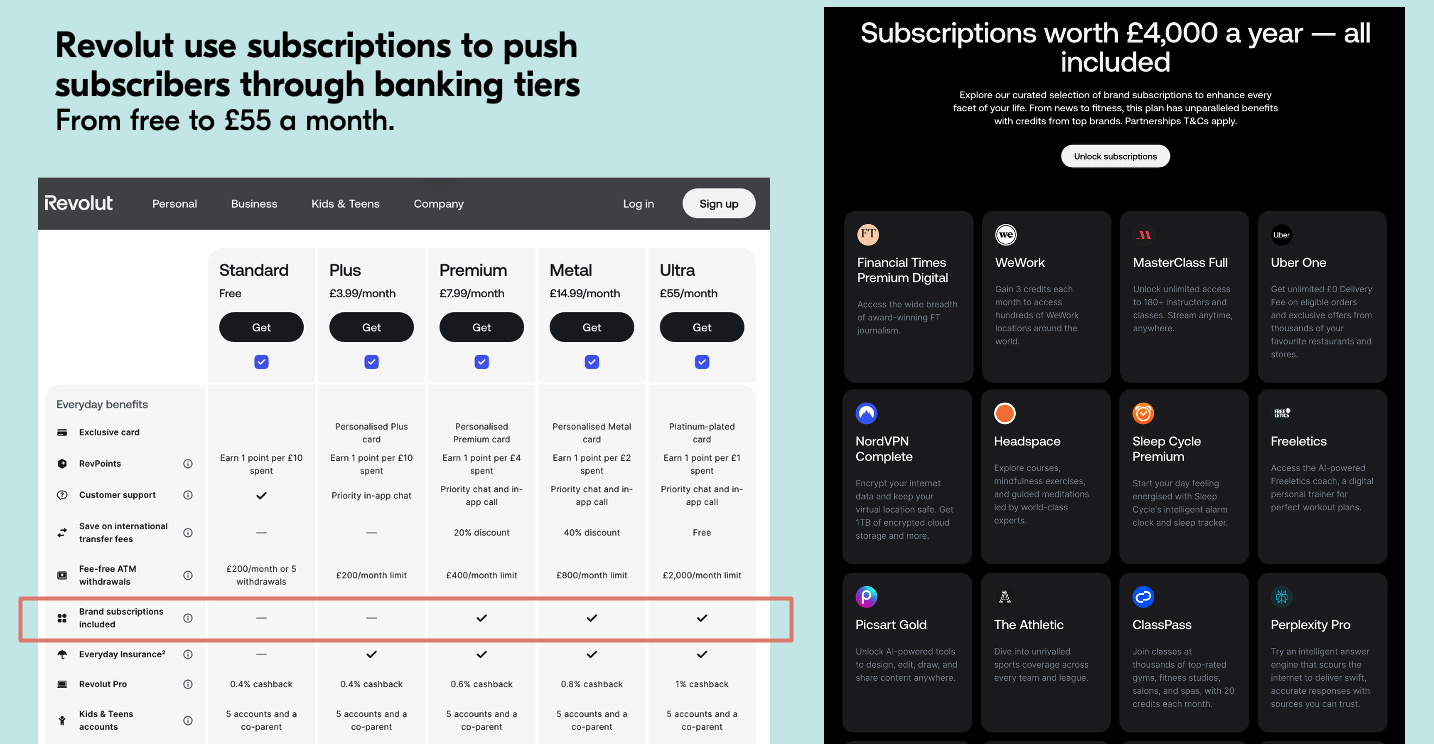
8. Subscriptions can create a clearer path to premium accounts
Traditional banks do not need to replicate Revolut’s proposition to apply the same principle. By adding greater subscription value at each account tier, banks can give customers a clearer reason to move from a free account to a paid plan and make the difference between tiers easier to understand.
9. AI will turn subscription management into a new battleground
Trust will determine which providers can turn that interest into adoption. Some 44% of subscribers do not trust any of the providers tested to offer an AI subscription management service, showing that consumers are interested in the outcome but cautious about handing over control.
10. Banks have a trust advantage but they do not own this market yet
Three in ten consumers, 29%, already consider banks the safest option for managing subscriptions in one place, rising to 44% among Gen Z and Millennials. That trust, combined with the bank’s existing role in payments and financial management, creates a credible foundation for subscription management.
However, telcos, retailers and wallets are pursuing the same customer relationship. Each wants to become the place where consumers discover, pay for and manage a growing range of digital services.
Trust will only become a competitive advantage if banks turn it into a better experience. That means giving customers a branded subscription hub where they can activate, manage and upgrade services without leaving the banking environment. If banks do not establish that relationship, another provider will.
From expectation to action
Subscription bundling is moving beyond the edges of bank loyalty programs. Consumers increasingly expect it, many would switch for it and those already receiving subscriptions through their bank say it makes them more loyal.
The opportunity is not simply to add another perk. It is to make the account more useful by helping customers access, manage and save money on services that form part of their everyday lives. Done well, that can strengthen acquisition, increase engagement, support premium account revenue and give customers a more compelling reason to stay.
The Digital Vending Machine® (DVM™) from Bango gives banks, neobanks and wallet providers the technology and subscription ecosystem to deliver that experience. It brings subscription offers, activation, billing, upgrades and management into one branded customer journey, without requiring the bank to build and operate every connection itself.
Watch: How the Digital Vending Machine® supports subscription bundling for banks
Banking on loyalty report
Watch Bytesize webinar
Loyalty pays
Consumers expect more than cashback or one-off rewards. Discover how subscription bundling helps...
Download now